
Back to Resources
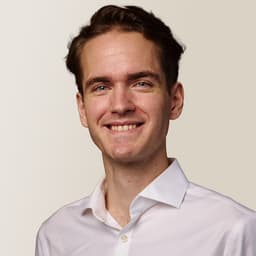
A mathematical finance researcher who develops deep learning and reinforcement learning methods for financial decision problems. Work includes neural network solutions to optimal stopping, deep empirical risk minimization for stochastic control in finance, and an inverse reinforcement learning method using anchor actions, presented at the International Conference on Machine Learning.
- amreppen@bu.edu
- Website
- https://max.reppen.ch/
- Publications
- Google Scholar
Classes taught
Last verified: October 3, 2026
Suggest a correction